Winner of the New Statesman SPERI Prize in Political Economy 2016


Showing posts with label Philippe Legrain. Show all posts

Friday, 16 November 2018

Brexit. Of course everyone hates a compromise, but like much else its the best option, isn't it?


This is the argument put forward by May and her supporters, but rather more significantly it is also the case argued by Martin Sandbu here and other very rational and realistic people. When you have two sides implacably opposed, compromise is often the way forward. No one likes the compromise, but that is the nature of compromises. It a mature democracy where we don’t want to be at our throats all the time, compromise is inevitable.

Labour are actually arguing the same thing. They just think they can get a better compromise, and they have a good case because they will not have to constantly try and appease a large group of Brexiters. But they can only do this when in power, and so if they do not get the General Election they want then all options are open, including arguing for Remain in a second referendum. This too can make sense. If May’s compromise is worse than Remaining, and Labour cannot implement their better compromise, then it makes sense for Labour to campaign for Remain. It is a sensible case that I have yet to hear Labour leaders make, but give them time say supporters.

I want to argue something very different. Let me start with an analogy. You have been feeling unwell for some time. Someone suggests you take some snake oil that they say will make you feel much better. Another person, who happens to be a doctor, says snake oil will do you harm and your ills have other causes that cannot be fixed quickly. You really want your problems cured soon. A third, wise person tells you to compromise: try the snake oil but with half the recommended dose. A compromise seems sensible, so that is what you do. Your temperature soars to 104 and you end up in A&E.

I think this analogy is more accurate than the traditional two sides and compromise idea proposed by May, Labour and Martin Sandbu. The snake oil was sold with the big lie that we could leave the EU, gain sovereignty, reduce immigration but keep the economic benefits of being in the EU. That lie was believed by Leavers. Behind that was a second, more pervasive lie, which is that reducing EU immigration would improve access to public services and increase real take-home pay. In terms of the first lie, the deal May has done  keeps a few of the economic benefits of the EU but with a substantial loss of sovereignty. (The deal Labour wants to do keeps even more of the economic benefits but loses more sovereignty.) In terms of the economic dimension (public services, incomes) and sovereignty, a Brexit deal is either worse in one of these dimensions or both. It is difficult to know in what dimension people will be better off or feel happier.

But surely people were voting to leave the EU, and we would have at least done that. But the evidence suggests the EU was of little concern to voters until 2016. According to IPSOS Mori, only a few percent of people thought the EU was an important issue in 2010. In 2015 it only occasionally reached double figures. This strongly suggests that people voted Leave not because they wanted to leave the EU for its own sake, but for what they believed would be a consequence of leaving in some other dimension. This is the key to understanding why a compromise does not work.

Most Brexit voters will not be moderately happy with a deal that makes them worse off: they will not be happy at all. Most Brexit voters will not be moderately happy with a deal that gives the UK less say in the rules the UK has to obey than when in the EU: they will not be happy at all. A true compromise is something that gives each side something, but the incredible thing about Brexit is that what most Leavers want from Brexit is not possible, yet most politicians and much of the media refuse to tell them that.

The curse of Brexit is that anyone enacting it will be unpopular, not because most Leave voters do not get all they want but because they do not get anything they want. In fact, like the snake oil analogy, they will probably be worse off or have less say. Brexit was always a fantasy, and anyone who makes Brexit concrete will fail to deliver that fantasy. As most politicians have not had the courage to call Brexit out as the fantasy it is, voters are likely to blame the politicians who fail to produce their fantasy rather than blaming themselves.

May will keep telling lies, in the tradition of Brexit, to try and get her deal passed. She claimed outside Downing Street that she had secured our departure from Freedom of Movement. She has done no such thing. The final trade deal is still to be negotiated, and will not be known until after it is too late to change our mind. As pointed out here, the proposed Customs Union for mainland Britain is seriously incomplete. Once we have left the EU, we have no options left so we are in an even weaker position than we are now.

To say, as Philippe Legrain does here, that those arguing for Remain are playing Russian roulette with the UK economy are wrong. A majority of MPs asking for a referendum between May’s deal and staying in the EU is called democracy, and clearly if there was not a majority for such a referendum May’s deal is better than No Deal. The whole ‘taking a risk’ story is the result of deliberate choices by a Prime Minister that wants her deal passed on the basis of fear. MPs have to decide what deal is least worse for the UK, and that is clearly staying in the EU. 

In June 2016 we narrowly voted to Leave, when the Leave campaign claimed Turkey was about to join the EU and we would have more spending on public services if we left, in a campaign that used money that exceeded election rules the origins of which are still unclear. We now know that Turkey joining the EU is not on the horizon, according to the OBR there will be less money available for public services after we leave, and we will have to end up paying and obeying with no say over the rules. Our best estimates are that the UK economy is already 2.5% poorer as a result of Brexit, and on top of that the Brexit collapse in sterling has cut real wages. According to the lastest large poll two thirds of people want a say on the withdrawal agreement and there is a clear majority to Remain. Here is a similar YouGov poll. This is despite neither main political party arguing for the Remain option. It is time parliament respected the views of the people, not their hope 2 years ago when they were promised the moon but today when those promises have not been delivered.


Friday, 14 July 2017

Why German wages need to rise

An interesting disagreement occurred this week between Martin Sandbu and the Economist, which prompted a subsequent letter from Philippe Legrain (see also Martin again here). The key issue is whether the German current account surplus, which has steadily risen from a small deficit in 2000 to a large surplus of over 8% of GDP, is a problem or more particularly a drag on global growth.

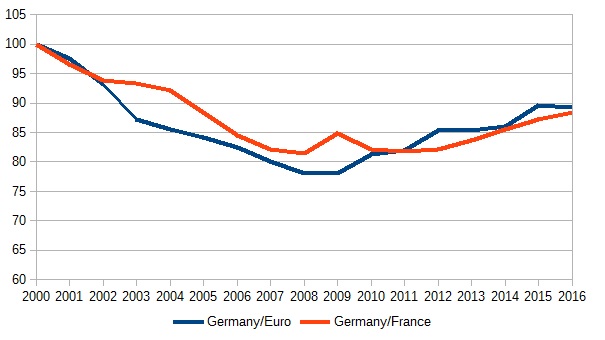
To assess whether the surplus is a problem, it is helpful to discuss a key reason why it arose. I have talked about this in detail many times before, and a similar story has been told by one of the five members of Germany’s Council of Economic Experts, Peter Bofinger. A short summary is that from the moment the Eurozone was born Germany allowed wages to increase at a level that was inconsistent with the EZ inflation target of ‘just below 2%’. We can see this clearly in the following chart.

Relative unit labour costs, source OECD Economic Outlook, 2000=100

The blue line shows German unit labour costs relative to its competitors compared to the same for the Euro area average. Obviously Germany is part of that average, so this line reduces the extent of any competitiveness divergence between Germany and other union partners. By keeping wage inflation low from 2000 to 2009, Germany steadily gained a competitive advantage over other Eurozone countries.

At the time most people focused on the excessive inflation in the periphery. But as the red line shows, this was only half the story, because wage inflation was too low in Germany compared to everyone else. This growing competitive advantage was bound to lead to growing current account surpluses.

However that in itself is not enough to say there is a problem, for two related reasons. First, perhaps Germany entered the Eurozone at an uncompetitive exchange rate, so the chart above just shows a correction to that. Second, perhaps Germany needs to be this competitive because the private sector wants to save more than it invests and therefore to buy foreign assets.

There are good reasons, mainly to do with an ageing population, why the second point might be true. (If it was also true in 2000, the first point could also be true.) It makes sense on demographic grounds for Germany to run a current account surplus. The key issue is how big a surplus. Over 8% of GDP is huge, and I have always thought that it was much too big to simply represent the underlying preferences of German savers.

I’m glad to see the IMF agrees. It suggests that a current account surplus of between 2.5% to 5.5% represents a medium term equilibrium. That would suggest that the competitiveness correction that started in 2009 has still got some way to go. Why is it taking so long? This confuses some into believing that the 8% surplus must represent some kind of medium term equilibrium, because surely disequilibrium caused by price and wage rigidities should have unwound by now. The answer to that can also be found in an argument that I and others put forward a few years ago.

For this competitiveness imbalance to unwind, we need either high wage growth in Germany, low wage growth in the rest of the Eurozone, or both. Given how low inflation is on average in the Eurozone, getting below average wage inflation outside Germany is very difficult. The reluctance of firms to impose wage cuts, or workers to accept them, is well known. As a result, the unwinding of competitiveness imbalances in the Eurozone was always going to be slow if the Eurozone was still recovering from its fiscal and monetary policy induced recession and therefore Eurozone average inflation was low. [1]

In that sense German current account surpluses on their current scale are a symptom of two underlying problems: a successful attempt by Germany to undercut other Eurozone members before the GFC, and current low inflation in the Eurozone. To the extent that Germany can make up for their past mistakes by encouraging higher German wages (either directly, or indirectly through an expansionary fiscal policy) they should. Not only would that speed adjustment, but it would also discourage a culture within Germany that says it is generally legitimate to undercut other Eurozone members through low wage increases. [2]

From this perspective, does that mean that the current excess surpluses in Germany are a drag on global growth? Only in a very indirect way. If higher German wages, or the means used to achieve them, boosted demand and output in Germany then this would help global growth. (Remember that ECB interest rates are stuck at their lower bound, so there will be little monetary offset to any demand boost.) The important point is that this demand boost is not so that Germany can help out the world or other union members, but because Germany should do what it can to correct a problem of its own making.

[1] Resistance to nominal wage cuts becomes a much more powerful argument for a higher inflation target in a monetary union where asymmetries mean equilibrium exchange rates are likely to change over time.

[2] The rule in a currency union is very simple. Once we have achieved a competitiveness equilibrium, nominal wages should rise by 2% (the inflation target) more than underlying national productivity. I frequently get comments along the lines that setting wages lower than this improves the competitiveness of the Eurozone as a whole. This is incorrect, because if all union members moderate their wages in a similar fashion EZ inflation would fall, prompting a monetary stimulus to bring inflation back to 2% and wage inflation back to 2% plus productivity growth.    

Tuesday, 8 September 2015

Making the Eurozone work better: sovereign default

Given the current problems in the Eurozone, it is understandable that many non-Eurozone economists remind us that they had doubts from the beginning. That, unfortunately, is not very helpful criticism, except in so far as it tells us how these problems were originally wished away. One lesson from the Greek tragedy is that voters' faith in the Euro project can survive even under tremendous strain. [1] The Euro was always a political project, and the political reasons for it have not gone away. For the governing elite of Europe this is likely to remain the case. So going backwards is not an option.

Yet while the people and the elite both want to keep the Euro, they part company when it comes to moving to a complete fiscal and political union: a United States of Europe. As Philippe Legrain notes, ever since the French and Dutch voted No, voter attitudes to further central control have hardened - and with good reason. If what he describes as the “Monnet method” (use any crisis to increase integration) continues, and as Andrew Watt points out it is continuing in a big way, the threat to the Eurozone could become existential. European policy makers have taken far too many liberties with democracy as it is: they should not take even more. Which is why I tend to get a little impatient with economists and institutions that spend a lot of time designed schemes for further substantial integration.

So the critical issue for now is whether the way the current union is run can be improved? I see three key unresolved areas here: sovereign default, competitiveness imbalances and the ECB. I talked about how to cope better with potential competitiveness imbalances recently. This post is about default.

I agree with Philippe Legrain that we need to have more decentralised fiscal control, and less rules from the centre. As I have noted before, there now exists in the Eurozone a system that is parallel to monitoring from Brussels, based instead on national fiscal councils. Can we design a system around that which negates any need for central control?

One way of making this work would be to deny any support to any EZ government that gets into trouble with the market. When the EZ was set up, its architects worried that market discipline would be too weak for this to work, so centralised controls were also necessary (the Stability and Growth Pact). In one sense they were right: the markets started treating Greek government debt as if it was German debt. But once a crisis happened they were wrong: governments with lower deficits than the UK were regarded as riskier by the markets.

What should now be clear is that the debt of member governments of a monetary union are subject to much greater rollover risk than equivalent countries outside the union because they do not control their own currency. That problem has been dealt with (for the moment) by OMT. But you cannot have OMT without conditions. For obvious reasons OMT cannot be a blank cheque to a monetary union member to run ever higher deficits.

So OMT has to be conditional, but who should set the conditions? Who decides that a future Greece has to default, but that a future Ireland should get the OMT guarantee without the need to default? At the moment the answer is both the other Eurozone governments and the ECB decide. But Eurozone governments have shown themselves to be hopeless at this task (see actual Greece), partly because they are subject to pressure from creditors. To leave this all to the unelected, unaccountable ECB is just asking for problems, and would represent too great a strain on ECB independence.

Let’s imagine the following. The Italian government at some time in the future finds that interest rates on its debt begin to rise well above average Eurozone levels. We get into a situation where a self-fulfilling default is possible. Should the ECB supply OMT cover to end that possibility or not? What conditions should be imposed on Italy as the price for that cover?

It would be nice if we could write down some simple rules (even complex rules) that could choose between a Greece and an Ireland. Fabian Lindner discusses some possibilities here. The major problem is that a great deal depends on something that embodies a political judgement: just how large will future primary surpluses be? Italy, because of its large debt, is used to running much larger primary surpluses than other countries. How do you judge what the upper limit is?

This is why ‘leaving it to the market’ is so attractive, because you appear to be asking a huge number of people to take a bet on the answer. But that method is flawed, because with rollover risk what they are actually taking a bet on is what they think other market participants think about rollover risk. OMT removes that rollover risk.

So if the market cannot do this, and the ECB and EZ governments should not do this, who is left? Do we set up a new institution of experts to decide and set conditions? (Conditions have to be set, because actions may change after OMT is granted.)

One obvious response is that we do not need a new institution, because we already have one, and it is called the IMF. It is imperfect, with at the moment too much influence from EZ governments on its decisions, but that means reforming the IMF rather than reinventing it. This may happen as a result of the Greek debacle. Philippe Legrain suggests using the IMF in a similar role here, although as a transitional measure while a new EZ institution is set up. However it is difficult to imagine EZ governments setting up a new institution that was truly independent of political pressure from member states.

The proposal would work like this. When Italy got into difficulties, it would go to the IMF. No EZ assistance would be allowed before this. The IMF would decide what level of default (if any) was required. The IMF, and not EZ governments, would set any conditionality thought necessary to return deficits to a sustainable level. That would include a path for deficits that the country could reasonably achieve without creating unnecessary unemployment. (If the country was uncompetitive, some unemployment would be inevitable.)

If Italy agreed to those conditions, then OMT would automatically be extended by the ECB. It is quite possible that in those circumstances Italy would regain market access at reasonable rates. If it did not, the IMF (and NOT other EZ governments) should provide the finance necessary to cover transitional deficits.

I suspect this scheme would not be attractive to many Eurozone policy makers, because they would be losing influence and control. But a better way to think about it is that the Eurozone contracts out (to the IMF) the tricky business of deciding whether a government’s debt is sustainable or not. That seems to me to be a small price to pay to avoid the kind of conflict between governments that became so clear in the recent Greek ‘negotiations’.

[1] Of the countries polled here, only two had more people thinking the euro had been bad rather than good for their country: Italy and Cyprus. See also Andrew Watt here.